Future of Digital Banking in U.S. by 2026: 4 Key Innovations
Anúncios
Latest developments on Digital Banking Innovations in the U.S. by 2026, with key facts, verified sources and what readers need to monitor next in Estados Unidos, presented clearly in Inglês (Estados Unidos) (en-US).
The landscape of financial services in the United States is undergoing a profound transformation, driven by an accelerating pace of technological advancement. By 2026, the future of digital banking in the U.S. will be irrevocably shaped by several groundbreaking innovations, fundamentally altering how consumers interact with their money and how institutions operate.
This shift is not merely an upgrade of existing systems; it represents a paradigm change, moving towards more intelligent, integrated, and user-centric financial experiences. Understanding these key innovations is crucial for anyone navigating the evolving financial ecosystem.
This article delves into four pivotal innovations that are set to redefine Digital Banking Innovations, offering a comprehensive look at their implications and what lies ahead for consumers and financial institutions alike.
The financial sector is witnessing a rapid evolution, with technology acting as the primary catalyst. This transformation is driven by consumer demand for convenience, personalization, and efficiency, pushing traditional banks and fintech companies to innovate at an unprecedented rate.
Anúncios
The competitive landscape is intensifying, forcing institutions to adopt cutting-edge solutions to retain and attract customers. The regulatory environment is also adapting, creating both opportunities and challenges for these emerging technologies.
As we approach 2026, the convergence of various technological advancements promises a banking experience far removed from the conventional models. This evolution is not just about digitalizing existing processes but reimagining the very essence of financial interaction.
Artificial Intelligence and Machine Learning Reshaping Customer Experience
Artificial Intelligence (AI) and Machine Learning (ML) are at the forefront of the revolution in digital banking. These technologies are no longer confined to experimental labs; they are actively being integrated into core banking operations, promising to deliver unparalleled customer experiences and operational efficiencies.
From intelligent chatbots providing instant support to sophisticated algorithms detecting fraud in real-time, AI and ML are becoming indispensable. Their ability to process vast amounts of data allows for predictive analytics, offering proactive financial advice and personalized product recommendations.
This pervasive integration will fundamentally alter how customers interact with their banks, making services more intuitive, responsive, and tailored to individual needs, a critical component of Digital Banking Innovations.
Hyper-Personalization Driven by Data Analytics
AI-powered analytics enable banks to move beyond generic offerings, creating highly personalized financial products and services. By analyzing spending habits, income patterns, and financial goals, AI can anticipate customer needs and suggest appropriate solutions.
This level of personalization extends to budgeting tools, investment recommendations, and even loan approvals, making financial management feel less like a chore and more like a guided journey. The goal is to build stronger, more trusting relationships between banks and their clients through deeply understood individual requirements.
Anúncios
- AI analyzes transaction history for spending insights.
- ML algorithms predict future financial needs.
- Personalized product recommendations enhance customer loyalty.
- Proactive financial advice improves financial wellness.
The continuous learning capabilities of ML models mean that these personalized experiences will only improve over time. As more data is gathered and processed, the accuracy and relevance of AI-driven insights will increase, leading to an even more refined and responsive banking ecosystem.
Blockchain and Distributed Ledger Technology for Enhanced Security
Blockchain and Distributed Ledger Technology (DLT) are poised to revolutionize the underlying infrastructure of digital banking. While often associated with cryptocurrencies, their true potential lies in their ability to provide secure, transparent, and immutable records of transactions, which is vital for the future of Digital Banking Innovations.
By decentralizing data storage and verification, blockchain can significantly reduce the risk of fraud and cyberattacks, a persistent concern in the financial sector. This enhanced security builds greater trust among users and institutions, fostering a more resilient financial system.
Furthermore, DLT can streamline complex interbank transactions, reducing settlement times and operational costs, ultimately benefiting both financial institutions and their customers.
Streamlining Cross-Border Payments
One of the most significant applications of blockchain in banking is in cross-border payments. Traditional international transfers can be slow, expensive, and opaque, involving multiple intermediaries and complex reconciliation processes.
Blockchain technology offers a direct, real-time, and cost-effective alternative, enabling instant settlements and greater transparency. This efficiency will be particularly beneficial for businesses engaged in international trade and individuals sending remittances.
The reduction in friction and cost associated with these transactions will unlock new economic opportunities and foster greater global financial inclusion.
- Blockchain ensures immutable transaction records.
- DLT reduces fraud and enhances security.
- Cross-border payments become faster and cheaper.
- Increased transparency in financial transactions.
The adoption of blockchain will require significant collaboration among financial institutions and regulators to establish common standards and protocols. However, the long-term benefits in terms of security, efficiency, and cost savings make it an inevitable component of the future of Digital Banking Innovations.
Embedded Finance and Banking-as-a-Service (BaaS)
Embedded finance represents a paradigm shift where financial services are seamlessly integrated into non-financial platforms and applications. This means that banking functionalities, such as payments, lending, and insurance, are offered directly at the point of need, often without the user even realizing they are interacting with a bank.
Banking-as-a-Service (BaaS) is the technological backbone enabling this integration, allowing third-party developers to build financial products on top of a bank’s regulated infrastructure. This collaborative model fosters innovation and expands the reach of financial services beyond traditional banking channels, marking a significant step in Digital Banking Innovations.
The convenience and contextual relevance of embedded finance will redefine customer expectations, making financial transactions an invisible part of everyday life.
Financial Services at the Point of Need
Imagine purchasing a car and getting instant financing options directly within the dealership’s app, or receiving embedded insurance for a new gadget at the e-commerce checkout. This is the promise of embedded finance – making financial decisions effortless and integrated into the customer journey.
This approach moves banking from a destination to an inherent part of other services, reducing friction and enhancing user experience. For businesses, it opens new revenue streams and opportunities to deepen customer relationships by offering value-added financial solutions.
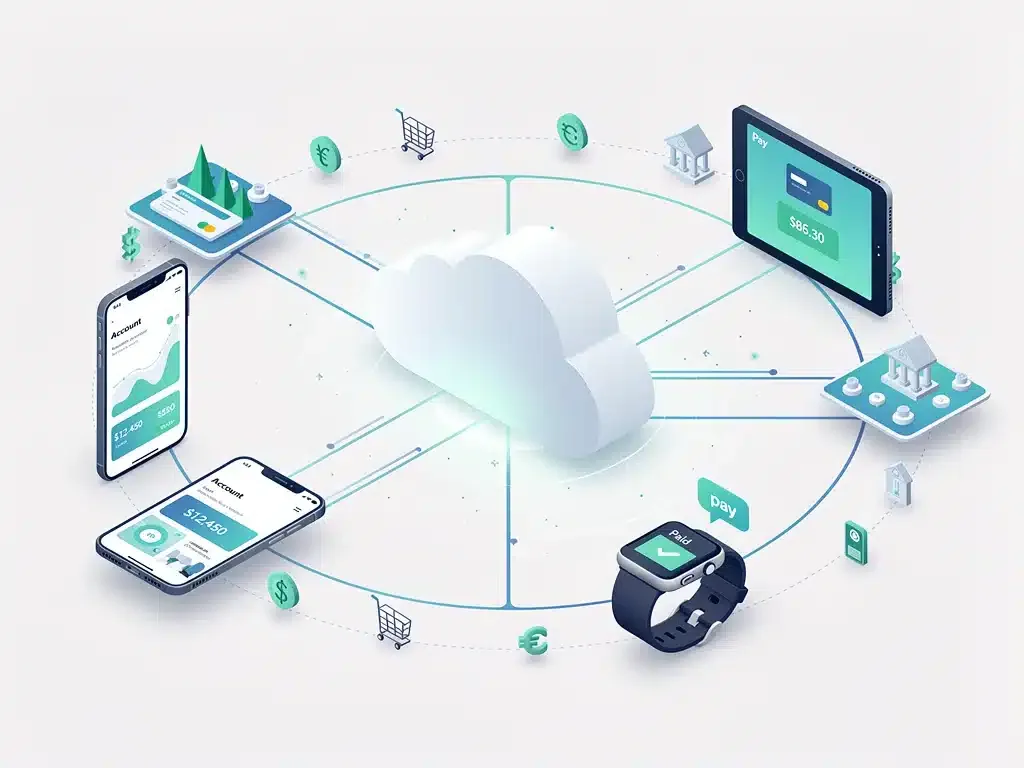
The growth of embedded finance will also drive increased competition, pushing traditional banks to either adopt BaaS models or partner with fintechs to remain relevant in this evolving landscape. The focus shifts from owning the customer relationship to enabling financial interactions wherever they occur.
Open Banking and API-Driven Connectivity
Open Banking, facilitated by Application Programming Interfaces (APIs), is a critical enabler of the future of digital banking. It allows third-party financial service providers to securely access customer financial data (with explicit consent), fostering a more interconnected and innovative financial ecosystem.
This open approach encourages collaboration between traditional banks, fintech startups, and other service providers, leading to a wider array of financial products and improved customer choice. APIs act as secure bridges, enabling seamless data exchange and functionality sharing across different platforms, which is central to Digital Banking Innovations.
The result is a more dynamic and competitive market, where consumers benefit from tailored services, better rates, and a more holistic view of their financial health.
Empowering Consumers with Data Control
At its core, Open Banking is about giving consumers greater control over their financial data. By consenting to share their data, individuals can access services that were previously unavailable or required significant manual effort, such as aggregated financial dashboards, personalized budgeting apps, and instant loan applications.
This transparency and interoperability empower users to choose the best financial products for their needs, rather than being limited to a single provider. It also encourages banks to compete on the quality and innovation of their services, rather than relying on customer inertia.
- APIs enable secure data sharing between institutions.
- Consumers gain control over their financial data.
- Increased competition leads to better financial products.
- Holistic financial management becomes more accessible.
While regulatory frameworks are still evolving to support Open Banking fully in the U.S., the clear benefits for consumers and the drive for innovation will ensure its continued expansion. It is a cornerstone of a truly integrated and customer-centric digital banking future.
The Rise of Central Bank Digital Currencies (CBDCs)
The concept of Central Bank Digital Currencies (CBDCs) is gaining significant traction globally, and the U.S. Federal Reserve is actively exploring a digital dollar. A CBDC would be a digital form of a country’s fiat currency, issued and backed by the central bank, offering a secure and stable digital alternative to privately issued cryptocurrencies.
The introduction of a CBDC could have profound implications for the U.S. financial system, affecting everything from payment systems to monetary policy. It promises increased efficiency in payments, enhanced financial inclusion for underserved populations, and greater stability in the digital economy, significantly impacting Digital Banking Innovations.
While challenges remain, the potential benefits are driving serious consideration and development in this area.
Implications for Payment Systems and Financial Inclusion
A U.S. CBDC could fundamentally alter the payment landscape, offering a direct, instant, and secure method for transactions. This could reduce reliance on commercial banks for payment processing, potentially lowering fees and speeding up settlements.
Crucially, a digital dollar could provide access to financial services for the estimated 7 million unbanked households in the U.S., enabling them to participate more fully in the digital economy. It would offer a stable and universally accepted digital payment instrument, reducing barriers to entry for many.
The design and implementation of a CBDC would need to carefully consider privacy concerns, cybersecurity risks, and its impact on the existing financial ecosystem. However, its potential to modernize infrastructure and promote equity makes it a key innovation to watch.
Cybersecurity and Fraud Prevention in a Digital Age
As digital banking advances, so too do the sophistication and frequency of cyber threats. Protecting customer data and financial assets from fraud and cyberattacks is paramount for maintaining trust and ensuring the stability of the financial system. Therefore, robust cybersecurity measures are not merely an add-on but an integral part of Digital Banking Innovations.
Financial institutions are investing heavily in advanced security protocols, including multi-factor authentication, biometric verification, and AI-driven threat detection systems. The challenge lies in balancing enhanced security with a seamless user experience, ensuring that protective measures do not hinder accessibility or convenience.
Continuous vigilance and adaptation to new threats are essential to safeguard the integrity of digital banking operations.
Leveraging AI for Real-Time Threat Detection
AI and Machine Learning play a crucial role in modern cybersecurity strategies. These technologies can analyze vast streams of transaction data in real-time, identifying unusual patterns or anomalies that may indicate fraudulent activity.
Unlike traditional rule-based systems, AI can adapt to new attack vectors and evolving fraud schemes, providing a more dynamic and effective defense. This proactive approach to threat detection minimizes financial losses and protects sensitive customer information.
Furthermore, AI can assist in predicting potential vulnerabilities and recommending preventative measures, creating a more resilient digital banking environment.
- Multi-factor authentication enhances account security.
- Biometric verification offers convenient and strong protection.
- AI detects fraudulent patterns in real-time.
- Continuous adaptation to new cyber threats is vital.
The ongoing battle against cybercrime necessitates a collaborative effort between financial institutions, technology providers, and government agencies. Sharing threat intelligence and developing industry-wide best practices are crucial for building a secure future for Digital Banking Innovations.
Regulatory Adaptation and Consumer Protection
The rapid pace of Digital Banking Innovations presents significant challenges for regulators. Striking the right balance between fostering innovation and ensuring consumer protection, financial stability, and market integrity is a complex task. Regulatory frameworks must evolve to accommodate new technologies and business models without stifling progress.
In the U.S., various bodies like the Federal Reserve, OCC, and CFPB are actively engaged in understanding and responding to these changes. Their efforts focus on developing clear guidelines for data privacy, cybersecurity, fair lending practices in AI-driven systems, and the oversight of new financial products.
Effective regulation is essential to build public trust and ensure that the benefits of digital banking are realized responsibly and equitably across all segments of the population.
Navigating the Evolving Regulatory Landscape
The regulatory environment for digital banking is characterized by its dynamic nature. New technologies often emerge faster than regulations can be codified, creating periods of uncertainty. Regulators are increasingly adopting a more agile approach, using sandboxes and pilot programs to test innovations in a controlled environment.
This allows for a better understanding of potential risks and the development of appropriate safeguards before widespread adoption. Furthermore, international cooperation on regulatory standards is becoming increasingly important, given the global nature of digital finance.
The ongoing dialogue between innovators and regulators is crucial for shaping a future where technology serves society without compromising safety or fairness.
The Future Outlook: Convergence and Collaboration
The trajectory of Digital Banking Innovations points towards an increasing convergence of technologies and a greater emphasis on collaboration. The lines between traditional banking, fintech, and even non-financial sectors will continue to blur, leading to a highly interconnected ecosystem.
Partnerships between established financial institutions and agile fintech startups will become the norm, leveraging the strengths of both – the trust and regulatory expertise of banks combined with the innovation and speed of fintechs. This collaborative spirit will accelerate the development and adoption of new solutions.
Ultimately, the future of digital banking in the U.S. by 2026 will be defined by its ability to deliver seamless, intelligent, and secure financial experiences that are deeply integrated into the daily lives of consumers.
This convergence will also necessitate a continuous focus on ethical AI, data governance, and inclusive design to ensure that technological advancements benefit all segments of society. The next few years promise a transformative period, reshaping the very fabric of financial interactions.
| Key Innovation | Brief Description |
|---|---|
| AI & Machine Learning | Drives hyper-personalization, fraud detection, and predictive analytics in banking services. |
| Blockchain & DLT | Enhances security, transparency, and efficiency for transactions, especially cross-border payments. |
| Embedded Finance | Integrates financial services seamlessly into non-financial platforms at the point of need. |
| Open Banking & APIs | Enables secure data sharing and collaboration, fostering innovation and consumer choice. |
Frequently Asked Questions About Digital Banking Innovations
What is the primary driver of digital banking innovation in the U.S.?▼The primary driver is a combination of evolving consumer expectations for convenience and personalization, coupled with rapid advancements in technologies like AI, blockchain, and cloud computing. The competitive landscape also pushes financial institutions to innovate continuously.
How will AI impact everyday banking for consumers?▼AI will lead to hyper-personalized services, offering tailored financial advice, proactive fraud detection, and seamless customer support through intelligent chatbots. It will make financial management more intuitive and responsive to individual needs and behaviors.
What role does blockchain play in the future of digital banking?▼Blockchain enhances security, transparency, and efficiency in banking. It’s crucial for secure record-keeping, reducing fraud, and streamlining complex transactions, particularly cross-border payments, by providing immutable and decentralized ledgers.
What is embedded finance and why is it important?▼Embedded finance integrates banking services directly into non-financial platforms, offering payments, loans, or insurance at the point of need. It’s important because it creates a seamless customer experience and opens new revenue streams for businesses by contextualizing financial offerings.
How are regulators adapting to these digital banking changes?▼Regulators are adopting agile approaches, using sandboxes and pilot programs to understand new technologies. They are developing guidelines for data privacy, cybersecurity, and fair practices to balance innovation with consumer protection and financial stability in the evolving digital landscape.
Looking Ahead
The transformative period for Digital Banking Innovations in the U.S. by 2026 is not merely a forecast but an ongoing reality. The convergence of AI, blockchain, embedded finance, and open banking will redefine financial interactions, making them more intelligent, integrated, and accessible. Staying informed about these developments is crucial for consumers to leverage new opportunities and for institutions to adapt and thrive. The focus will remain on user-centric design, robust security, and regulatory foresight to ensure a resilient and innovative financial future.